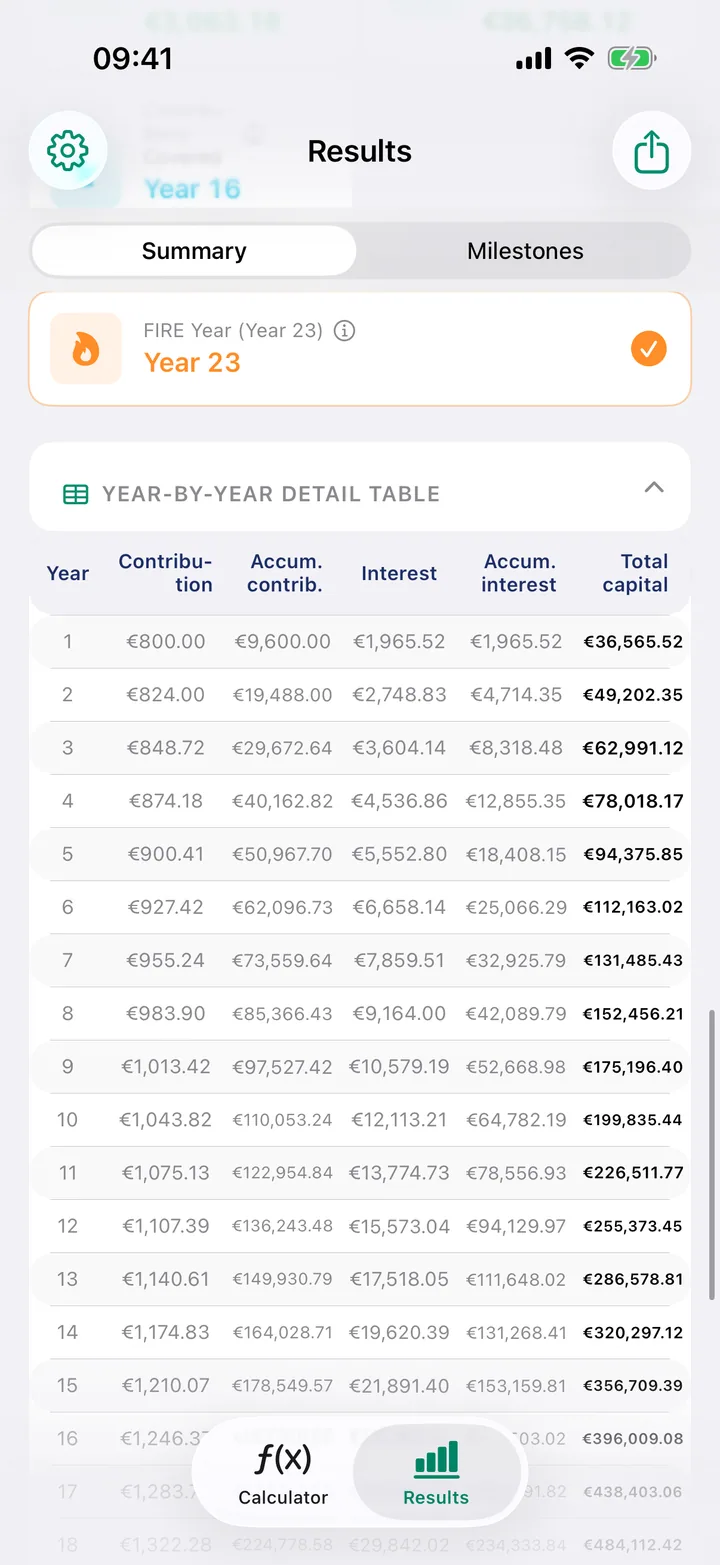
Year-by-year table
Contribution, accumulated contributions, interest, accumulated interest and total capital for every year.
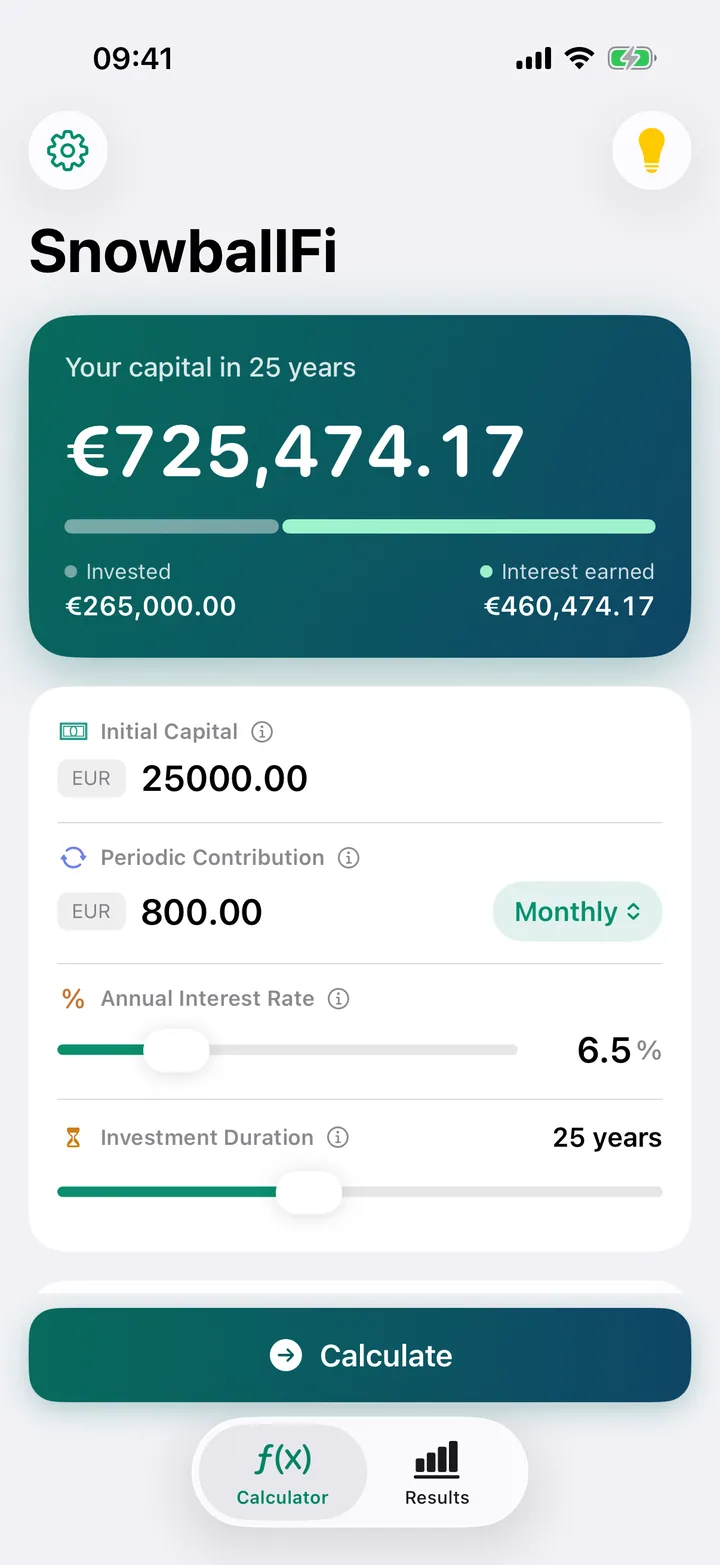
snowballFi projects investments with inflation, taxes and FIRE, then shows every year in charts and a full table.
Initial capital, periodic contribution, annual rate and years. The final capital updates while you type.
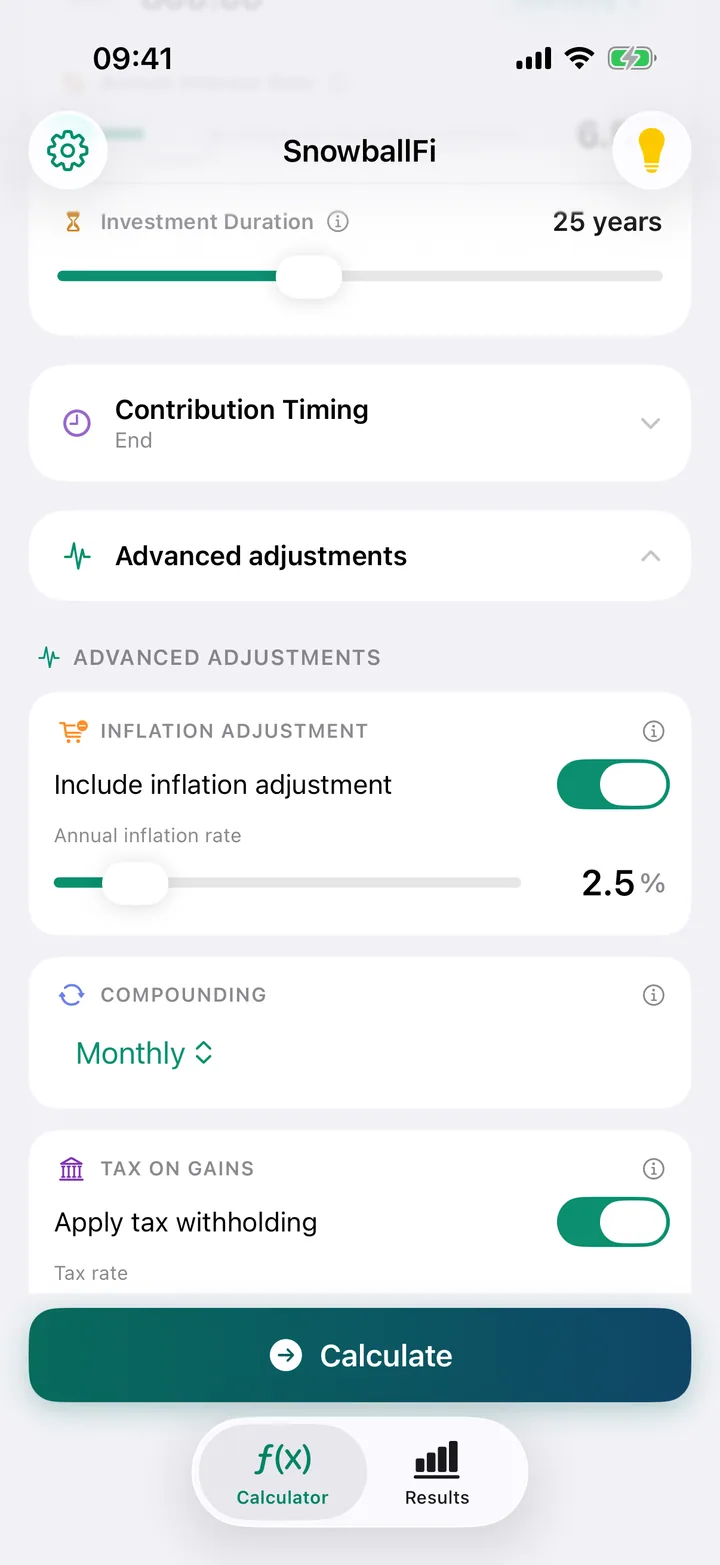
Switch on inflation, taxes and a personal FIRE target. Choose how often interest compounds.
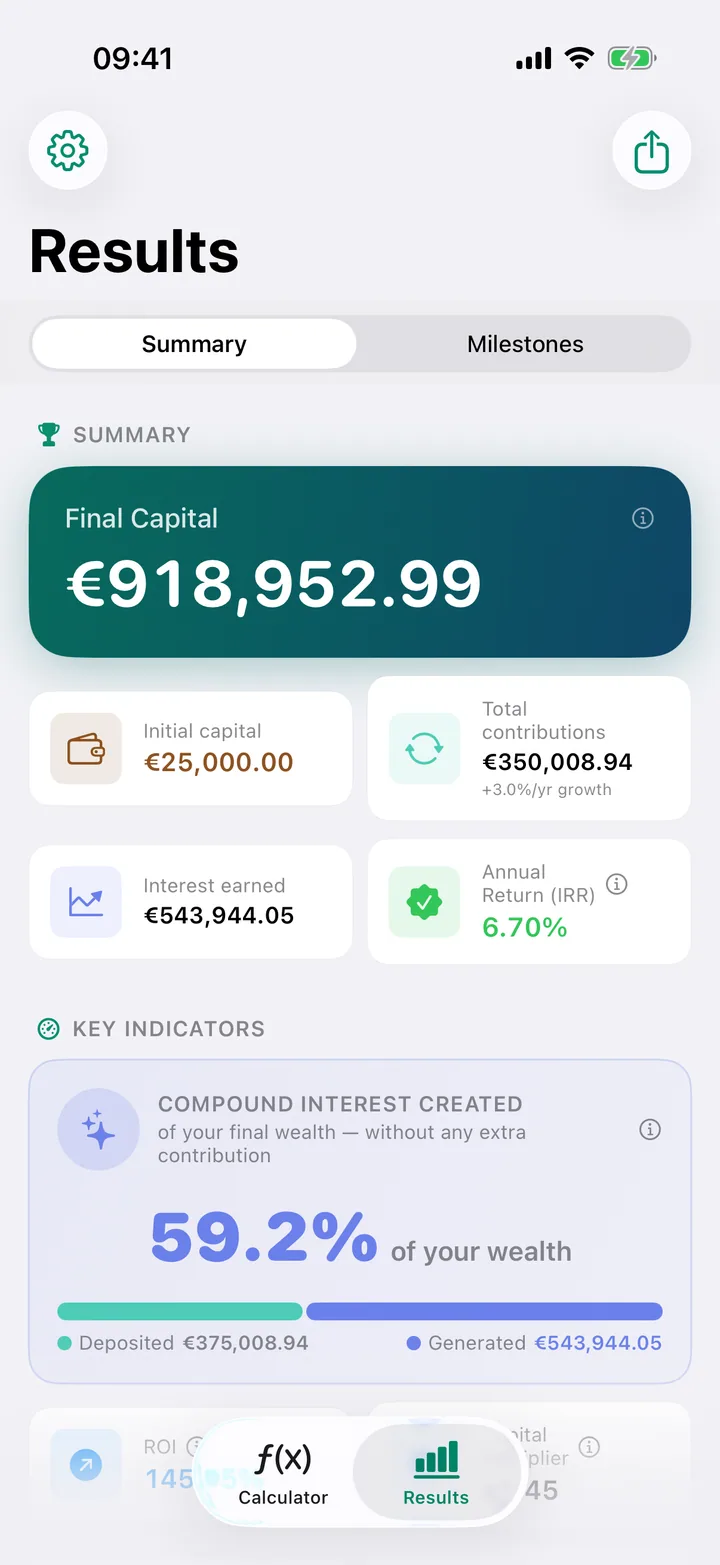
Final capital, money invested and interest earned, plus ROI, IRR, multiplier and time to double.
The year-by-year table shows contribution, accumulated interest and total capital for each year.
The projection, the charts and the table come from the same calculation, so the numbers always agree.
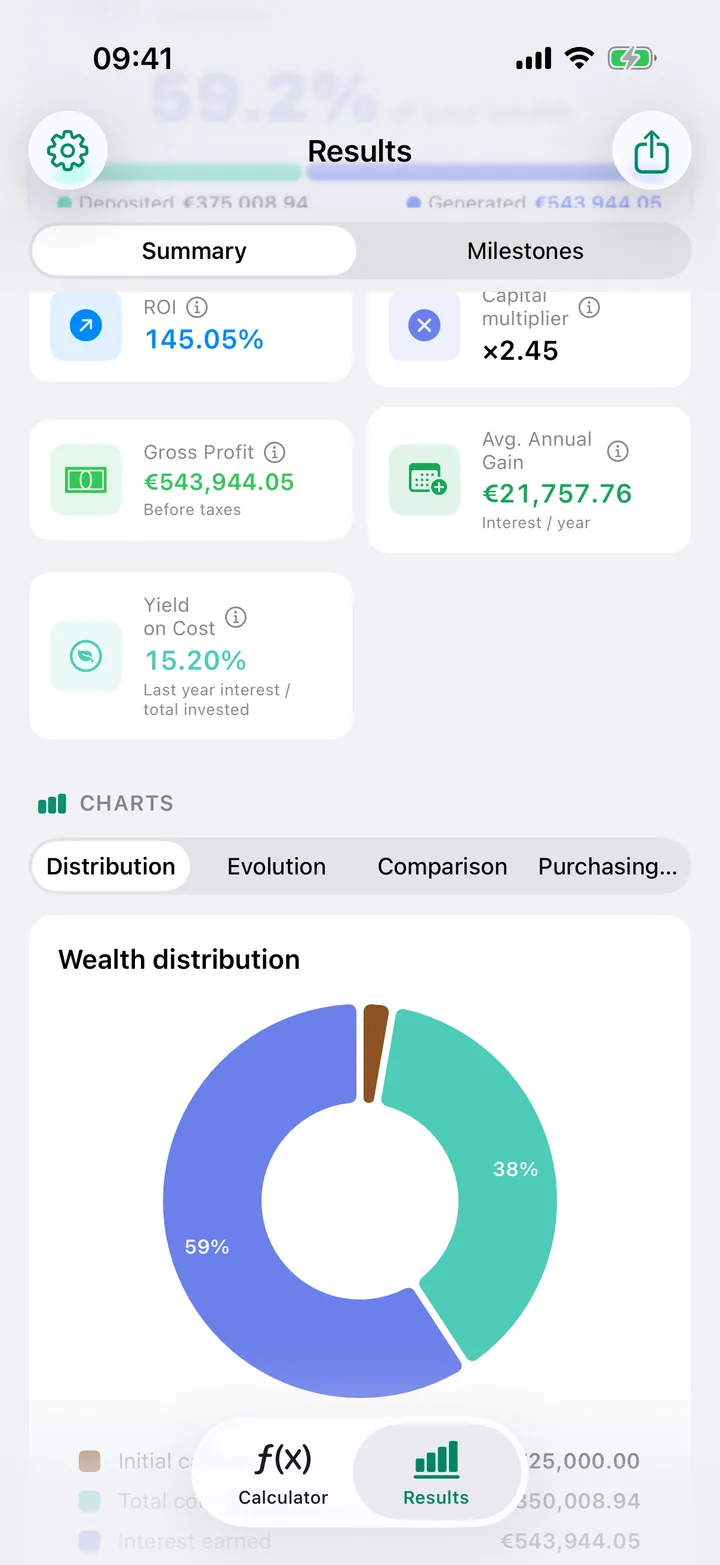
How much of the final capital is your money and how much is interest.
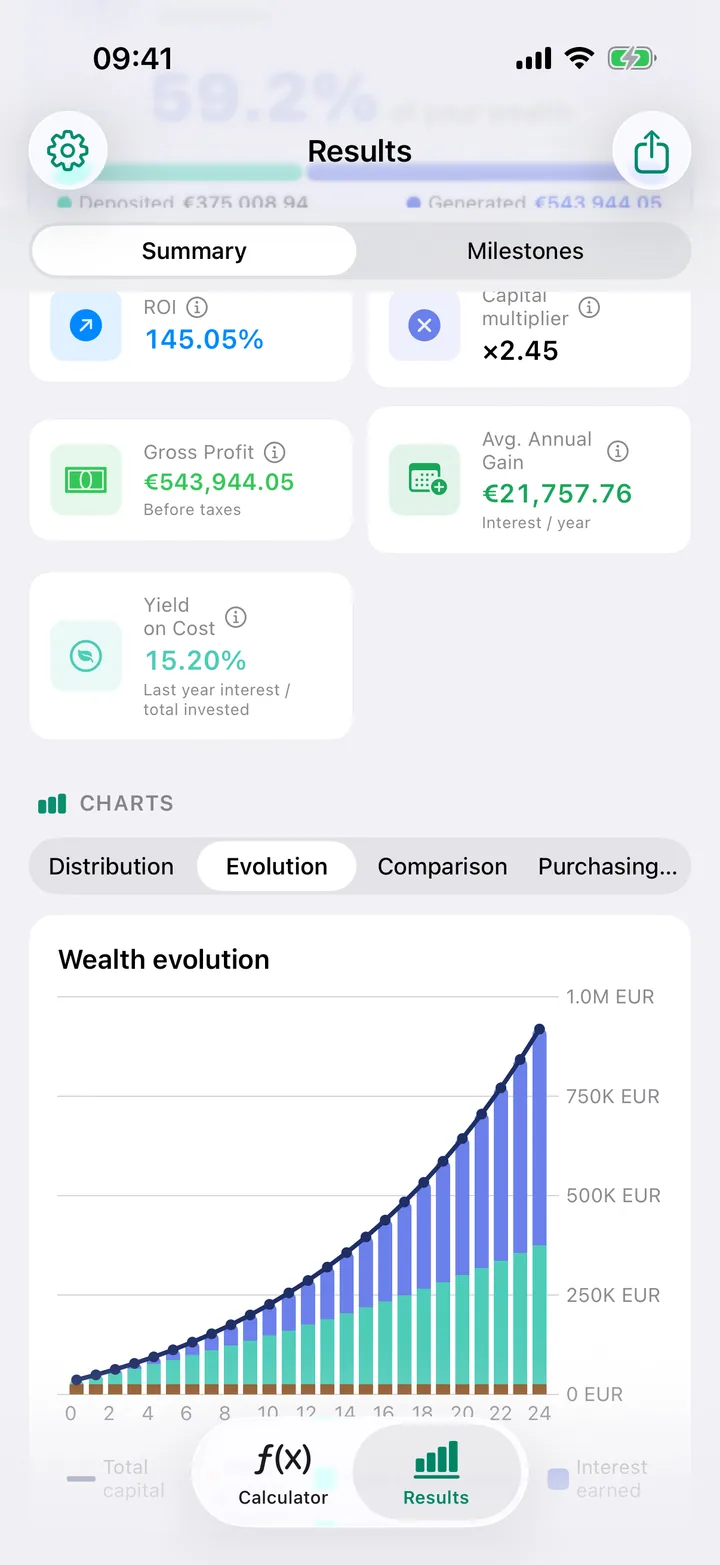
Stacked yearly bars: initial capital, contributions and interest.
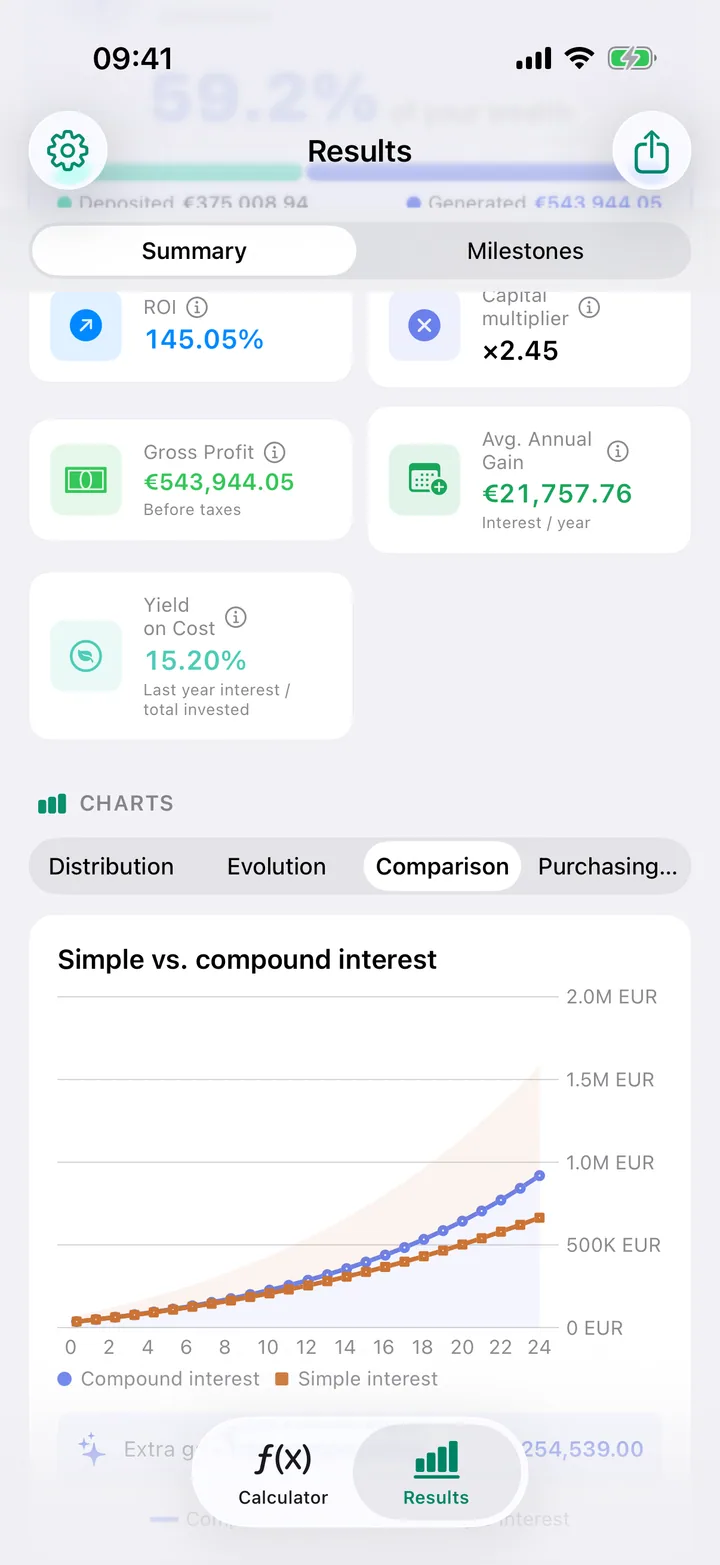
The gap between simple and compound interest, in currency.
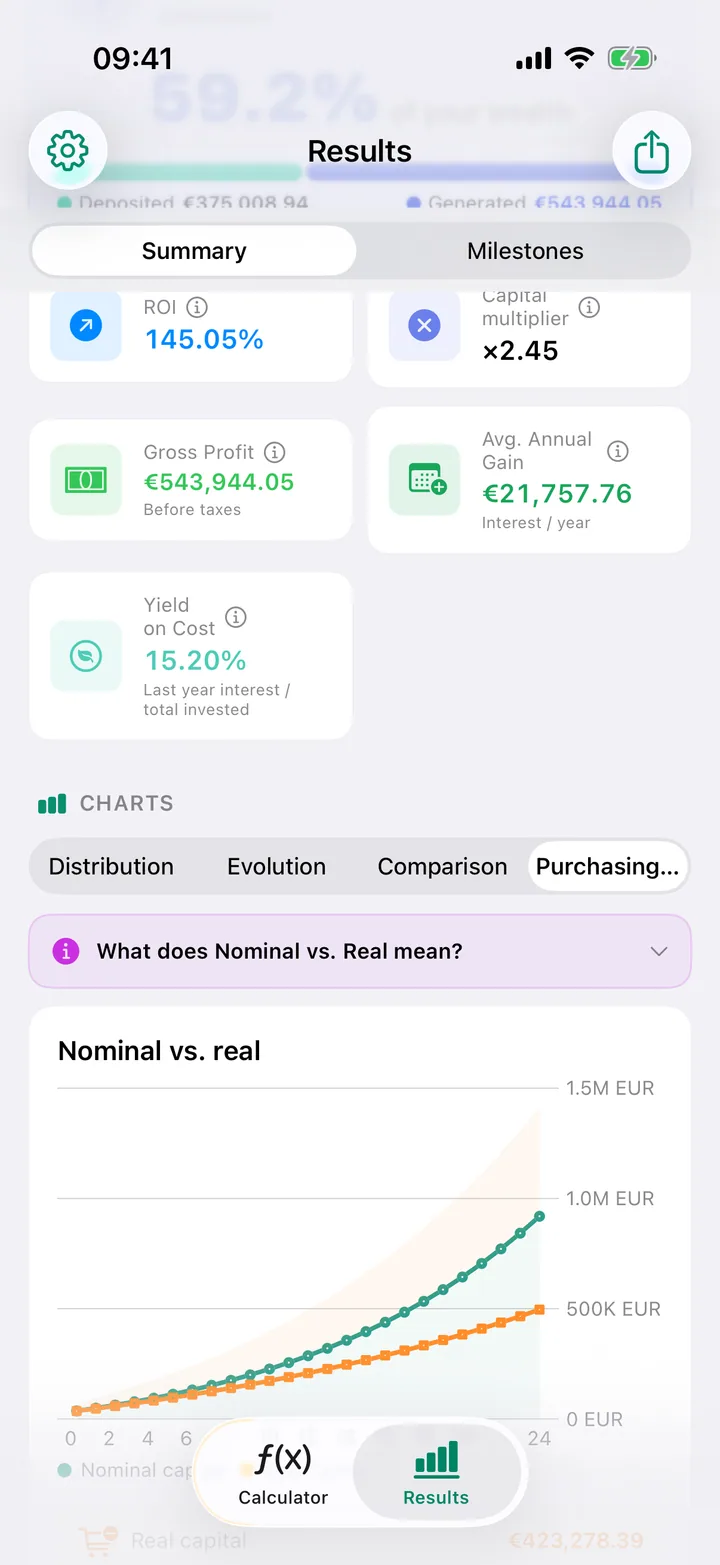
Nominal capital against real capital after inflation.
Switch each one on or off and watch the final capital change.
Contribution, accumulated contributions, interest, accumulated interest and total capital for every year.
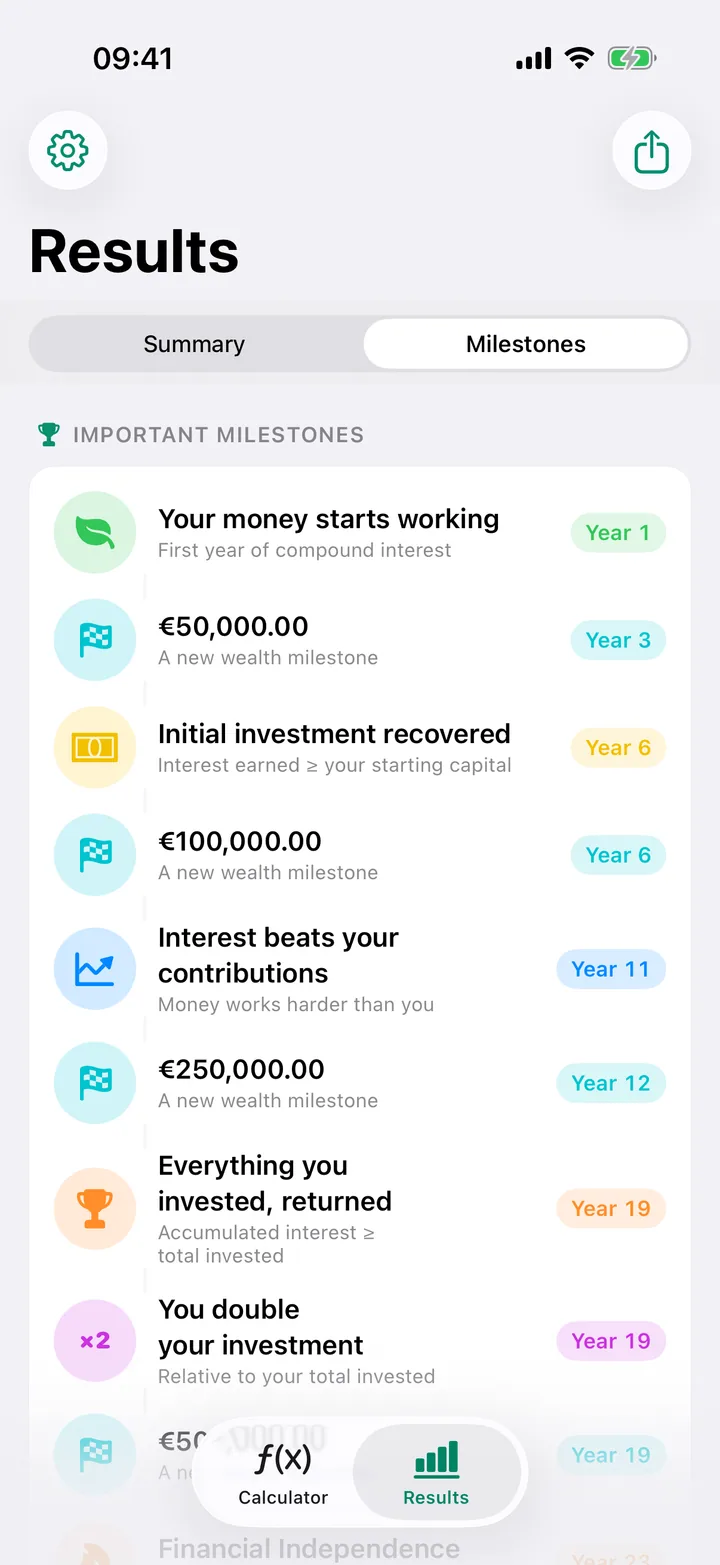
The year you pass 50,000, recover your initial capital or double your investment.
Money-weighted return, yield on cost and more, each explained in the in-app guide.
Compound interest is interest earned on your capital and on the interest already added. snowballFi divides the nominal annual rate by the compounding periods, the same convention as Excel FV and the HP 12C.
FV = P(1 + r/n)^(nt) + PMT x ((1 + r/n)^(nt) - 1) / (r/n)
The rule of 72 gives 72 / 6.5 = 11.1 years. The exact formula the app uses gives 10.7 years for a lump sum at 6.5% compounded monthly.
| Year | Invested | Interest | Capital |
|---|---|---|---|
| 5 | €73,000.00 | €18,109.61 | €91,109.61 |
| 10 | €121,000.00 | €61,527.12 | €182,527.12 |
| 15 | €169,000.00 | €139,940.83 | €308,940.83 |
| 20 | €217,000.00 | €266,747.91 | €483,747.91 |
| 25 | €265,000.00 | €460,474.17 | €725,474.17 |
Compound interest is interest calculated on the initial capital plus the interest already accumulated. Each period the earnings are reinvested, so growth accelerates over time.
It divides the nominal annual rate by the number of compounding periods and applies the future value formula with periodic contributions. This is the convention used by Excel FV and the HP 12C.
Yes. Inflation shows your real purchasing power. Taxes on gains can use a flat rate or Spain’s progressive savings brackets. Both are advanced adjustments.
FIRE means financial independence, retire early. The 4% rule estimates that a portfolio can support withdrawals of 4% of its value a year. snowballFi finds the year your portfolio reaches your monthly income goal.
The app is free and shows ads. A one-time purchase removes ads and unlocks the advanced adjustments and indicators. There is no subscription.
No. snowballFi projects the growth of savings and investments. It does not model debt or loan amortization schedules.
English, Spanish, German, French, Italian, Brazilian Portuguese and Hindi, with EUR, USD, GBP, CHF, BRL, INR, CAD and MXN.
Free on iPhone. Enter four numbers and see the next 25 years.